Mule Account Detection With AI: Finding Accounts That Move Fraud Money
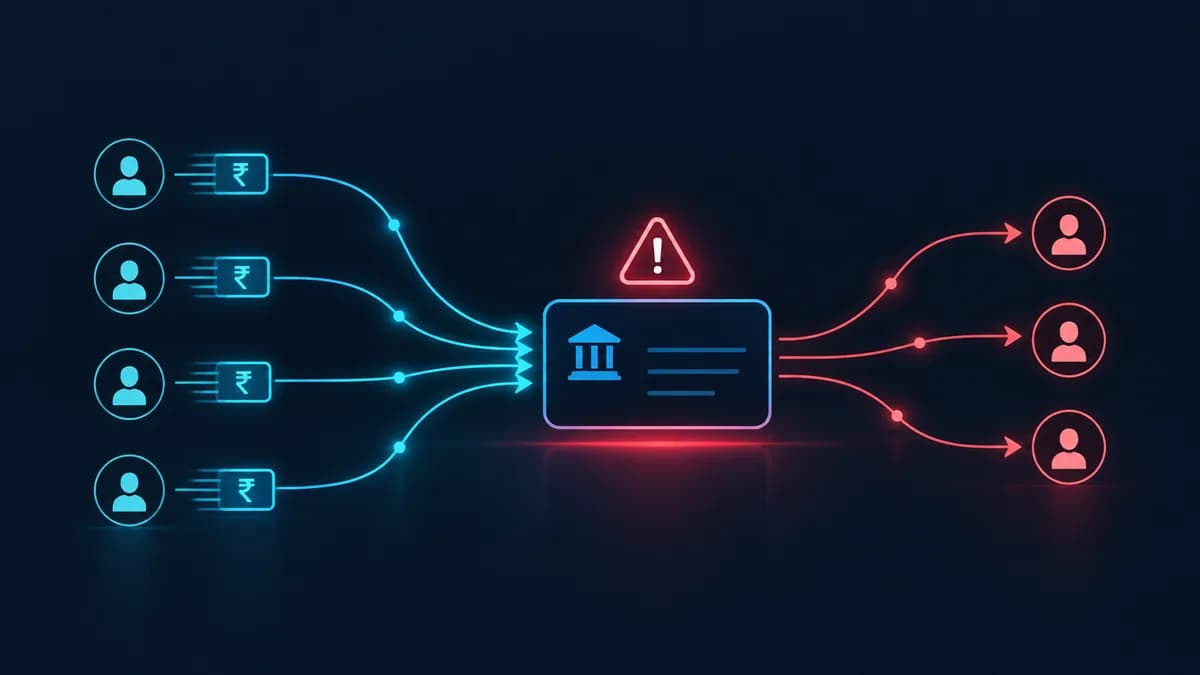
A savings account opened eight months ago by a college student has been quiet since it was opened. On a Tuesday afternoon it receives credits from dozens of unrelated UPI handles, each a few thousand rupees, and every credit leaves within minutes for a handful of new beneficiaries. The student was offered a small commission for "receiving payments for a friend's business". To the bank's transaction monitoring, each transfer looks ordinary. Mule account detection exists because the fraud is invisible one transaction at a time and obvious once you follow the money across accounts.
Why mule accounts defeat transaction-level rules
A mule account is a legitimate account, held by a real customer, used to receive and pass on the proceeds of fraud. That is precisely what makes it hard to catch. The KYC is genuine and the individual payments remain within normal limits. Rules written for single transactions, such as amount thresholds or unusual hours, see nothing worth stopping.
The obligation on the bank is direct. Indian banks must report suspicious transactions to FIU-IND and act on account-freeze requests routed through the National Cybercrime Reporting Portal, and supervisors expect institutions to detect mule activity on their own books before a police request arrives. Regulatory pressure on mule accounts has grown steadily. In December 2024 the Reserve Bank of India encouraged banks to adopt MuleHunter.AI, a model developed by the Reserve Bank Innovation Hub after studying 19 distinct patterns of mule activity with several banks. In May 2026 the Indian Cyber Crime Coordination Centre signed an agreement with RBIH to extend that work.
The constraint that shapes every design decision is time. Fraud proceeds rarely stay in a mule account for long, because the people orchestrating them know a freeze request may follow the victim's complaint. Detection that arrives the next morning, in a batch report, documents the loss and recovers none of it.
The position: a mule model is judged by its false positives
The common way to evaluate a mule model is detection rate, the share of confirmed mule accounts it flagged. That number matters, and it tells only half the story. The other half is what the model does to the honest customers whose behaviour resembles a mule's.
Those customers are numerous and easy to name. A delivery rider receives a daily payout and withdraws it the same evening. A small trader collects dozens of UPI payments at a weekly market and sweeps them to a supplier. A family member manages the household's transfers from one account. Each pattern shows many inbound credits and fast outward movement, which is the mule signature in its simplest form.
A model that freezes these accounts imposes a real harm on people who did nothing wrong, and in India's financial-inclusion segments that harm lands hardest on the customers with the least margin to absorb it. The case for a bank to defend before its board and its regulator is a model whose false positives are measured by segment and kept low enough that the response to a flag can be proportionate. A strong detection rate earns a model attention. False-positive discipline earns the right to act quickly on what the model finds.
Signals that follow the money across accounts
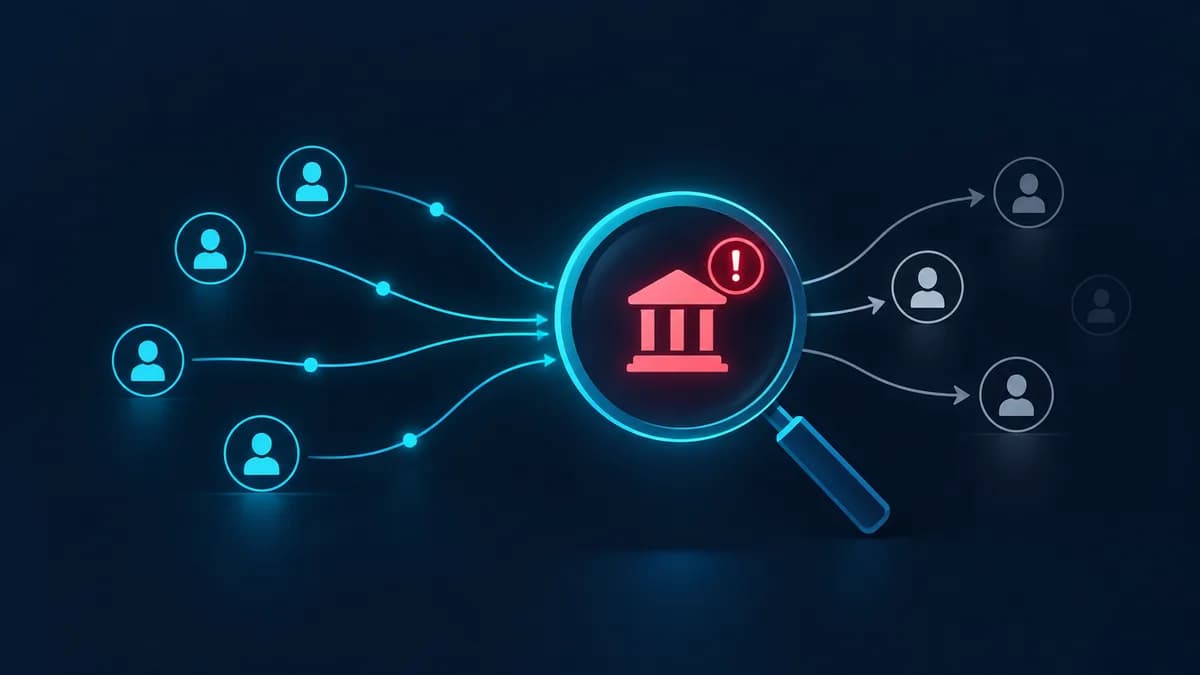
Effective detection treats accounts as nodes in a network and payments as the edges between them. The useful features describe how money moves through an account and who it moves with. Pass-through ratio measures how much of what arrives leaves again within a short window, and how long it stays before moving. Fan-in and fan-out count the distinct counterparties on each side. Network features add context a single account cannot supply, such as devices shared across accounts and clusters of accounts opened from the same location within days of each other.
Onboarding is the second place to look. Many mule accounts are opened for the purpose, and signals at account opening, such as a device already linked to other recently opened accounts, give the bank a chance to apply tighter limits before the first fraudulent credit arrives.
The response has to be graded to match the confidence. A low-confidence flag can trigger enhanced monitoring. A moderate one can prompt a verification call to the customer. A higher one can restrict transfers to new beneficiaries while leaving salary credits and bill payments untouched. A full debit freeze belongs to the cases where the evidence is strong or a valid request has arrived through the reporting portal. Every action carries reason codes recorded at the moment of decision, because the customer who calls the branch and the examiner who reviews the file will both ask why.
Labels for mule accounts arrive late and imperfectly. A confirmed mule is usually established through a victim complaint or a police request, often weeks after the funds moved. Teams that retrain only on confirmed cases learn the patterns of last quarter's fraud rings, so investigator feedback on reviewed alerts has to flow back into the model as a label in its own right.
The payout cycle that looked like laundering
A mid-sized bank deployed a network-based mule model and saw its alert volume rise sharply in the first week. Investigators found that a large share of the new alerts came from one segment: delivery and ride-hailing partners paid through a single payout aggregator. Their accounts received a credit every evening from the same source and emptied within the hour, to a few regular payees. The model read the pattern as pass-through behaviour and recommended freezes.
None of those freezes were executed, because the bank had set every early recommendation to route through investigator review. Had the model been wired to act on its own, a large group of working people would have lost access to a day's earnings.
The correction went into the features and the policy together. The model now derives baselines by segment, so a payout pattern is compared with other payout recipients instead of with salaried customers. Known corporate payers, verified through the bank's own onboarding of the aggregator, reduce the weight of inbound concentration. Restriction of new-beneficiary transfers replaced the freeze as the default action for medium-confidence flags, which stopped mule behaviour without touching the payouts.
Mule account detection is a race against funds that move in minutes, and AI gives banks the network view that rules never had. The harder discipline is proportion: acting fast on strong evidence while protecting the riders and small traders whose accounts resemble a mule's from the outside. A risk head reviewing a mule programme should ask for its false-positive rate by customer segment and for the share of flags that end in a full freeze. A programme that can produce both numbers, and explain each action it took, is one that delivers outcomes that survive scrutiny.
Related: Banking & Financial Services · Reserve Bank Innovation Hub: Automated grievance workflows with natural-language access and a complete audit record · IndusInd Bank Limited: AI-Powered Knowledge Source-Based Process Training and Query Resolution
Tell us the number you need to move.
…outcomes that survive scrutiny.